Start your 3-day free trial
Sign up to experience all premium features at no cost.
*Available only to new users. Each user is limited to one trial.

Before relying on credit card rental car coverage, read the Guide to Benefits for the exact card and trip. Confirm the renter, additional drivers, payment method, vehicle, country, rental length, business or personal use, and waiver decision, then identify liability, injury, belongings, roadside, and other gaps that the card benefit may not cover.
Key Takeaways:
- A card-network logo or travel-card label does not prove that your account includes rental coverage.
- Check eligibility before pickup and obtain written clarification for the exact itinerary.
- Use the required card and follow the guide's rules for deposits, final payment, points, and split tender.
- Separate collision or theft protection from liability, medical, personal-property, and roadside coverage.
- Save the agreement, condition record, receipts, and benefit confirmation even when no incident occurs.
Make the decision part of your international travel preparation, not a hurried answer at the rental counter. This guide covers the pre-rental check; an accident scene and a later damage invoice require separate response plans.
Identify the card product, issuer, account type, cardholder, and last four digits. Download the current Guide to Benefits and note its effective date. Save any previous version that may apply if the reservation, payment, and rental cross a benefit change.
Look for the formal benefit name. It may be called Auto Rental Collision Damage Waiver, Auto Rental Coverage, Car Rental Loss and Damage Insurance, or something else. Similar names can still have different activation rules, limits, exclusions, administrators, and claims paths.
Visa's consumer page says a Visa Signature card may offer auto-rental coverage, directs cardholders to the issuer for complete terms, and lists conditions such as using the covered card, being the primary renter, listing additional drivers, and declining the rental company's collision waiver.[1] The word “may” matters: confirm the actual account rather than treating the network page as your policy.
Record the administrator's contact details and ask for a coverage letter if the rental company or destination requires one. Give the administrator the country, dates, rental company, vehicle class, renter, other drivers, residence, purpose, and payment plan. Preserve its answer, but read the guide because a general telephone assurance may omit an exclusion.
If the card is new, downgraded, converted, suspended, overdue, or scheduled to close, ask whether the benefit will be active throughout the rental and claim period. Do not assume benefits survive an account change.
Match the name on the card, loyalty profile, reservation, and rental agreement. Determine whether the covered person must be the primary renter and whether a spouse, domestic partner, employee, or other authorized driver qualifies. List every permitted driver on the agreement when required.
Check the complete itinerary, including pickup and return countries, cross-border travel, ferries, islands, one-way return, and any extension. Some benefits exclude particular countries or apply different rules based on residence. A verbal counter approval to cross a border does not prove that the card benefit follows.
Review the maximum rental duration and how consecutive agreements, extensions, exchanges, or back-to-back rentals are counted. Do not split one long rental into several contracts to evade a limit. Ask how a delayed return affects eligibility before the original period expires.
Confirm the vehicle category. Vans, trucks, motorcycles, high-value or exotic cars, antique vehicles, off-road vehicles, recreational vehicles, car-sharing rentals, peer-to-peer vehicles, and vehicles above a stated passenger or value threshold may be excluded. The Chase Sapphire Preferred Guide shows why a card-specific issuer's definitions for renter, vehicle, agreement, and transaction must be read together.[2] Its terms are not universal.
State whether the trip is personal, business, relocation, delivery, ride-hailing, racing, off-road, or otherwise specialized. The guide may treat use as carefully as vehicle type. If the planned use is not clearly included, obtain written clarification or arrange other protection.
Read exactly what must be charged to the covered account. Some benefits require the card to initiate and complete the rental transaction; others address rewards, vouchers, corporate billing, taxes, deposits, or split payments differently. Keep the reservation receipt, payment authorization, final invoice, and rewards record.
Ask these questions before paying:
Keep pending and posted transactions distinct. A rental-car deposit or preauthorization can reduce available credit without becoming a final charge. The preauthorization-hold guide explains that payment stage; it does not determine insurance eligibility.
At pickup, confirm the agreement shows the intended payment account and all eligible drivers. If the counter changes the card, renter, rental company, vehicle class, dates, or contract number, reassess the benefit before leaving.
If the covered card cannot handle the deposit, do not quietly use another card and assume protection remains. Ask the administrator and rental company for a compliant alternative, then document the decision.
Credit-card rental benefits commonly focus on physical damage to or theft of the rental vehicle, with defined towing, loss-of-use, or administrative costs. They may exclude liability for injury or damage to other people and property. Visa's public overview expressly describes physical damage, theft, certain towing, and loss-of-use rather than every risk created by driving.[1]
Build a coverage map before deciding what to decline:
| Risk layer | Possible source | What to verify |
|---|---|---|
| Rental vehicle damage or theft | Card benefit or rental CDW/LDW | Covered events, exclusions, deductible, limit |
| Third-party liability | Rental company, personal policy, statutory scheme | Injury and property limits, territory, drivers |
| Driver and passenger injury | Health, travel, motor, or personal accident cover | Emergency care, exclusions, repatriation |
| Personal belongings | Travel, homeowners, renters, or separate cover | Vehicle-theft conditions and valuables |
| Roadside and mechanical issues | Rental company or assistance plan | Towing, lockout, tire, battery, fuel, breakdown |
| Diminished value and fees | Contract, card benefit, other insurer | Loss of use, administration, appraisal, exclusions |
Ask whether the card benefit is primary or secondary in your circumstances. Primary may mean it responds before some personal motor insurance; secondary may require another insurer's decision first. The answer can depend on residence, jurisdiction, vehicle, and other available insurance.
The FTC recommends checking personal auto insurance and credit-card benefits before buying optional rental coverage, and comparing what the rental company offers.[3] Do not decline a waiver until you understand both the card benefit and every uncovered layer.
If you are traveling internationally, confirm whether your personal motor policy follows you and whether local law mandates coverage through the rental company. A coverage letter does not override local law or the rental contract.
Identify each product offered at checkout or the counter. Collision damage waiver, loss damage waiver, supplemental liability, personal accident, personal effects, roadside service, tire or glass packages, and excess reduction are not interchangeable. Ask for the price and terms separately without assuming “full coverage” has a standard meaning.
If the card guide requires you to decline the rental company's CDW or LDW, confirm which line items count as that waiver and how mandatory local coverage is treated. Visa's public page describes declining the rental company's collision waiver as one condition for the benefit it summarizes.[1] Another card can use a different rule.
Do not decline unrelated liability or medical protection merely because the card covers collision damage. Conversely, do not assume accepting a limited tire, glass, or mandatory package necessarily cancels the card benefit. Ask the administrator about the exact product name and keep the written answer.
Review the rental contract for prohibited roads, geographic areas, drivers, uses, fuel, keys, reporting duties, alcohol or drug exclusions, unattended vehicle rules, and required police reports. A breach can affect the rental-company waiver, card benefit, or both.
If an unwanted product appears on the agreement, correct it before signing or use the unrequested-rental-insurance guide. Take a clear copy of the signed agreement and final selection screen.
Record why you accepted or declined each layer. The goal is not to minimize every fee; it is to avoid an uninsured risk or duplicate coverage you did not intend.
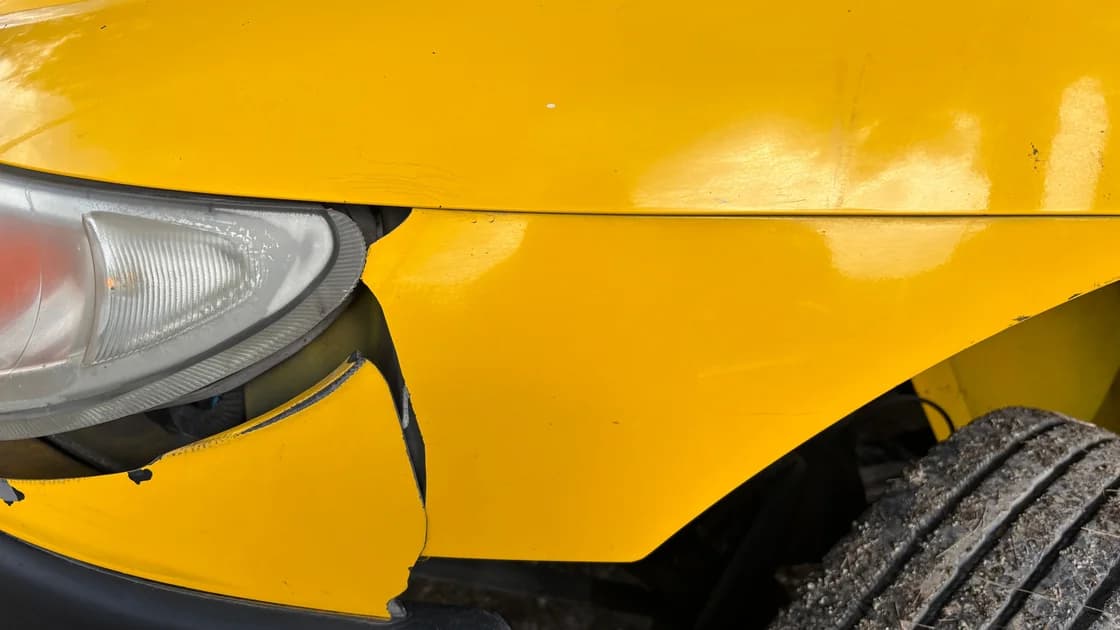
At pickup, photograph the vehicle from all sides, wheels, glass, roof, interior, fuel or charge level, mileage, keys, accessories, and every existing mark. Make sure the condition report includes disputed damage before departure. Keep the agreement and contact numbers offline.
At return, follow the contract's location, time, fuel, charging, key, and inspection process. Photograph the same areas, dashboard, parking position, and handoff. Obtain a final receipt or return acknowledgment. If returning after hours, use the documented after-hours return process when relevant.
If an accident occurs, protect people and follow local duties first. Then notify the rental company and benefit administrator as required; the rental-car accident guide covers the scene, authorities, evidence, towing, and consistent reports.
For a later invoice, do not assume the card benefit automatically validates or invalidates the rental company's charge. Request the agreement, before-and-after condition evidence, inspection, repair records, calculation, and benefit decision. Use the rental-car damage-charge guide for that stage.
Keep one record containing the guide, coverage letter, reservation, agreement, driver list, payment proof, waiver decisions, condition photographs, return receipt, and all incident or claim records. Update it if the rental is extended or the vehicle is exchanged.
No. Benefits vary by issuer, card product, account status, country, and effective date. Use the Guide to Benefits for the exact account.
No. It may focus on damage to or theft of the rental vehicle and leave liability, injury, personal belongings, roadside service, or other losses outside its scope.
Many benefits require it, but the exact rule and treatment of mandatory local coverage vary. Check the card guide and ask about the specific counter product.
It depends on the benefit, residence, trip, and other insurance. Read the coordination provision and ask the administrator how it applies to your circumstances.
Possibly, but rewards, vouchers, split tender, deposits, and final charges can be treated differently. Obtain an answer for the exact rewards program and payment path.
Only if they satisfy the guide and rental agreement. List every permitted driver when required and do not let an unlisted person drive.
No. Coverage comes from contracts, policies, payments, people, vehicles, and local law, not from the network used to read or save documents.
Disclaimer: This guide provides general travel and record-keeping information, not legal, financial, insurance, driving, or claims advice. Coverage and duties depend on the card, policies, rental contract, itinerary, and jurisdiction.
Sources checked 6 September 2026.
Related Reading:
Sign up to experience all premium features at no cost.
*Available only to new users. Each user is limited to one trial.