Start your 3-day free trial
Sign up to experience all premium features at no cost.
*Available only to new users. Each user is limited to one trial.
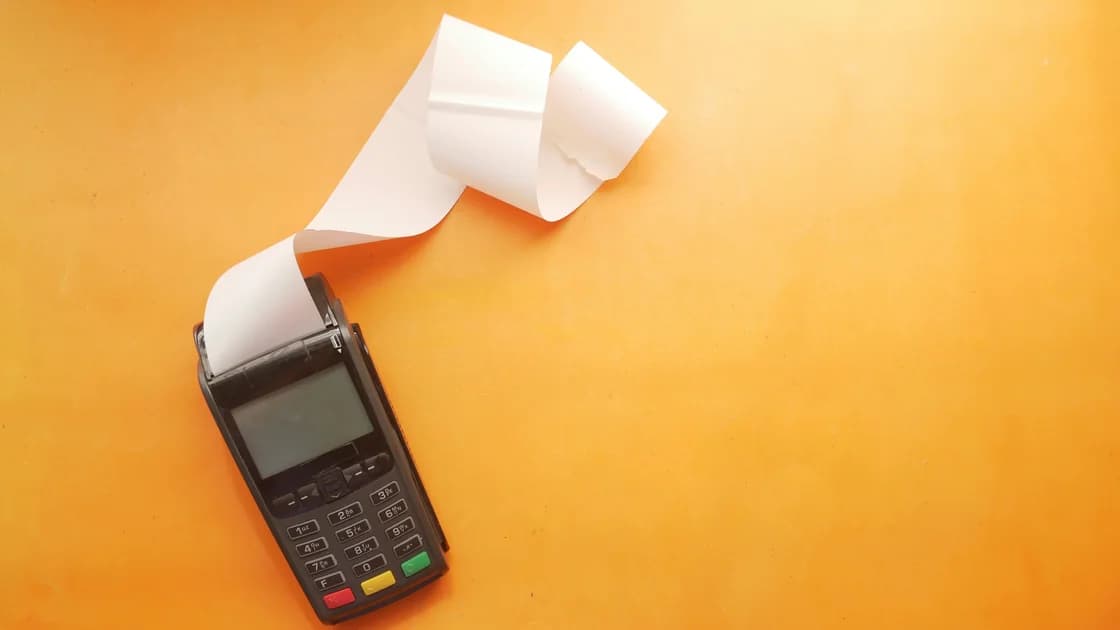
Chinese travelers can pay abroad more reliably by preparing two independent methods, carrying a limited amount of local cash, and checking the transaction currency before approving a card payment. No card network, mobile wallet, or QR code is guaranteed at every merchant, so the goal is graceful failure rather than one “universal” method.
Key Takeaways:
- Confirm overseas use with the issuing bank, not only the card logo.
- Keep two payment paths that do not depend on the same phone, card, or account.
- Check the amount and transaction currency before entering a PIN or approving a wallet prompt.
- Save issuer and card-network support routes separately from the wallet holding the card.
This is one part of a broader international travel preparation plan. It does not replace current advice from your bank, card network, merchant, or destination authorities.
Ask each issuing bank whether the specific card is enabled for overseas purchases, ATM use, contactless payments, and online transactions. Check how the bank wants you to report travel, what its current authentication route is, and how to freeze the card without the phone that normally receives codes.
Build a small payment inventory:
| Method | Primary role | Main dependency | Backup question |
|---|---|---|---|
| Physical card A | Routine merchant payments | Issuer approval and merchant acceptance | Can card B work on a different network or account? |
| Physical card B | Independent fallback | Separate issuer, account, or storage location | Is it stored away from card A? |
| Mobile payment | Convenient supported transactions | Phone, battery, wallet, network, merchant | Can you still pay if the phone is unavailable? |
| Local cash | Small transport, tips, or cash-only needs | Safe storage and change | Is the amount limited to likely short-term needs? |
| Emergency transfer | Replenishment after a disruption | Identity checks and trusted recipient | Have you verified the official route in advance? |
Do not keep every card, phone, and identity document in one wallet. Independence matters more than the number of logos you carry.
Use the method with the clearest amount, currency, and receipt. At a staffed merchant, a physical card or supported mobile wallet may offer a better audit trail than an informal transfer. For small cash-only situations, use cash without exposing the rest of your travel funds.
UnionPay says cardholders should confirm overseas transaction service with the issuer or its customer service before travel. Its help center also provides separate entries for exchange rates, card-use instructions, ATM lookup, and overseas support numbers.[1][2] These resources help you prepare, but an online logo or map entry is not a live acceptance guarantee.
If a card is declined, stop after a reasonable retry. Check the merchant amount, network, issuer alert, and whether another method is safer. Repeated attempts across several terminals can make a simple acceptance problem look like account abuse.
The terminal or ATM may present more than one currency. Before approving, read the currency code, amount, exchange-rate disclosure, and any additional fee shown on the screen or receipt. If you do not understand the choice, ask the merchant or stop the transaction rather than guessing.
UnionPay's FAQ describes its usual overseas card flow as spending in local currency with settlement converted according to its network arrangements.[2] The help center states that its displayed exchange rate does not include any extra fee an issuing bank may charge.[1] Your card product and issuer terms determine the final posting.
Keep the receipt until the transaction appears correctly. Do not let a staff member take the card out of sight, and cover the keypad when a PIN is required.
A mobile wallet can reduce how often a physical card is handled, but it concentrates payment, authentication, messaging, and battery risk in one device. Confirm that the wallet, card, destination, and merchant all support the transaction; a familiar app at home does not guarantee overseas acceptance.
Keep one physical method available. If the phone is lost, use the ordered digital recovery plan for a lost phone abroad before adding cards to an unfamiliar replacement device.
Your mainland number may still be needed for issuer alerts or recovery. The mainland phone-number continuity checklist explains how to reduce dependence on a single SMS path.
Carry enough for realistic short-term needs such as transport, food, or a cash-only venue, not the entire trip budget. Split it between secure locations, keep only a small working amount accessible, and follow local cash declaration and payment rules.
Use an ATM in a controlled location when possible. Verify the machine belongs to the institution shown, inspect the card slot, shield the keypad, and stop if the currency or fee disclosure is unclear. An ATM search result is a planning aid, not proof that the machine is operational or safe at that moment.
Never accept an offer from a stranger to exchange money, “test” your card, or move funds through a personal account. Official exchange, bank, and licensed payment channels provide a clearer dispute trail.
A useful backup survives the failure of the primary method. Two cards in the same phone wallet, funded by the same account and authenticated by the same lost SIM, are not truly independent.
Design the pair around separate failure points:
Tell a trusted contact how to verify an emergency request. A pre-agreed question or video call is safer than trusting a new number claiming to be you.
For a decline, read the terminal message, check the issuer app through a trusted route, and switch methods if the cause remains unclear. Do not share a one-time code with a cashier or caller.
For a lost card or phone, freeze affected payment methods through an official app, website, or number you independently find. Protect the primary email and mobile line, preserve receipts and alerts, and notify the issuer of unauthorized transactions.
If a caller claims to be a consulate or police officer and asks you to transfer “safe funds,” stop. The consular scam response guide explains how to hang up and verify independently. For general online-banking network boundaries, see whether a VPN is safe for online banking.
No. Acceptance, network access, battery, wallet status, and issuer controls can all differ. Carry a physical backup and limited local cash.
Not necessarily. The exact card, issuer controls, terminal routing, merchant configuration, and current network state all matter. Treat directory information as planning help, not a guarantee.
Read the currency, amount, rate, and fee disclosure before deciding. Network and issuer settlement rules differ, so confirm your own card terms rather than following a universal slogan.
Some issuers use travel notices and others rely on automated controls. Ask the issuing bank what it currently requires and how to recover access without your usual phone.
Cash avoids some card and network failures but cannot be remotely frozen or recovered. Carry a limited amount and split it between secure locations.
Record the ATM institution and location, contact the operator and issuing bank through official channels, and freeze the card if control is uncertain. Do not accept help from a stranger asking for a PIN.
No. A VPN cannot override issuer risk controls, merchant acceptance, identity checks, or payment-network rules. Follow the issuer's official recovery and verification process.
Disclaimer: This article provides general travel and payment-preparation information, not financial, legal, tax, foreign-exchange, or issuer-specific advice. Follow current instructions from your issuing bank, card network, merchant, and destination authorities.
Sources:
Sources checked 24 August 2026.
Related Articles:
Sign up to experience all premium features at no cost.
*Available only to new users. Each user is limited to one trial.